
Mark Anderson | November 9, 2026 | Car Accidents

A serious car accident can create financial problems, especially when a leased vehicle is involved. You may suddenly find yourself without transportation while still facing payments under your lease agreement.
If a leased car is totaled in Texas, the insurance company generally pays the vehicle’s actual cash value. However, the leasing company usually receives the settlement proceeds. You may still owe money if the insurance payment does not cover the amount required to terminate your lease.
Understanding how insurance settlements, lease agreements, and GAP coverage work can help you avoid unexpected expenses.
What Does It Mean When a Leased Car Is Totaled?
A vehicle is considered a total loss when an insurance company determines that repairing it is not economically practical. Insurers compare a vehicle’s market value with its estimated repair cost. If repairs would cost approximately as much as the vehicle is worth, the insurer may declare it totaled.
The insurance company generally pays the vehicle’s actual cash value (ACV), which accounts for depreciation. For example, a vehicle originally worth $40,000 might have a market value of only $28,000 when an accident occurs. The insurer generally bases its settlement on the current value rather than the original purchase price.
Who Receives the Insurance Payment for a Totaled Leased Car?
Unlike a financed or fully owned vehicle, a leased car legally belongs to the leasing company. Consequently, the leasing company generally has the right to receive the insurance proceeds when the vehicle is declared a total loss.
The insurer typically coordinates payment with the leasing company. However, the insurance settlement does not necessarily eliminate everything you owe. Depending on your lease agreement, you may remain responsible for outstanding payments, deductibles, or other charges.
If the insurance settlement exceeds the amount required to satisfy the lease, whether you receive any remaining funds depends on the agreement’s terms.
What Happens if Insurance Does Not Cover the Lease Balance?
One of the biggest concerns involving totaled leased vehicles is the difference between the insurance settlement and the amount owed under the lease.
For example, imagine the following:
- Your remaining lease payoff is $32,000
- Your vehicle’s actual cash value is $27,000
- The insurance company pays $27,000 toward the loss
- You face a potential shortfall of $5,000
Without additional protection, you may be responsible for the difference.
This situation is particularly common when a vehicle depreciates faster than the amount owed decreases.
Does GAP Insurance Cover a Totaled Leased Vehicle?
Guaranteed Asset Protection, or GAP coverage, can help protect drivers from certain financial losses. GAP coverage generally addresses the difference between the vehicle’s insurance settlement and the outstanding covered lease or loan balance.
Some vehicle leases include GAP protection automatically. Others require drivers to purchase the coverage separately. GAP coverage has limitations. Drivers should review their lease agreements and insurance documents to determine what protection they have.
What if Another Driver Caused the Accident?
If another driver’s negligence caused the collision, their liability insurance may cover the vehicle’s property damage. This is subject to available coverage limits and other rules. You may also have a separate personal injury claim if you suffered injuries.
Recoverable damages include both economic and non-economic damages. These losses may include medical expenses, lost wages, pain and suffering, and other qualifying damages.
Texas follows a modified comparative negligence rule. Under this rule, if you are 51% or more responsible for an accident, you generally cannot recover damages. If you are less than 51% liable, your recovery may be reduced according to your percentage of fault.
Contact Anderson Injury Lawyers To Schedule a Free Consultation With a Fort Worth Car Accident Attorney
Dealing with a totaled leased vehicle in Texas can be frustrating. It is more complex when insurance disputes and unexpected lease obligations make recovery more difficult. If another driver’s negligence caused your accident, don’t hesitate to get help.
Contact Anderson Injury Lawyers for a free consultation with a Fort Worth car accident lawyer today. We will investigate your crash, evaluate your insurance claim, and help you pursue the complete compensation you deserve.
We proudly serve Tarrant County, Dallas County, Travis County, and throughout Texas.
Anderson Injury Lawyers – Fort Worth Office
1310 W El Paso St, Fort Worth, TX 76102
(817) 294-1900
Find us with our GeoCoordinates: 32.74621197527774, -97.33552733508391
Anderson Injury Lawyers – Fort Worth Office (Secondary)
6618 Fossil Bluff Dr # 108, Fort Worth, TX 76137
(817) 631-4113
Find us with our GeoCoordinates: 32.86241013538118, -97.30973893918065
Anderson Injury Lawyers – Dallas Office
408 W Eighth St Suite 202, Dallas, TX 75208
(214) 327-8000
Find us with our GeoCoordinates: 32.748815542196404, -96.82524302658787
Anderson Injury Lawyers – Austin Office
811 Nueces Street, Austin TX, 78701
(512) 399-5000
Find us with our GeoCoordinates: 30.307794623518102, -97.73755898409242
About the Author
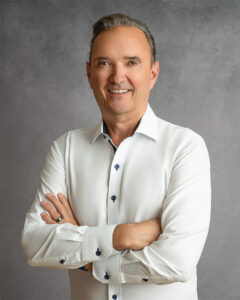
Mark A. Anderson is the founder of Anderson Injury Lawyers and a Board Certified Personal Injury Trial Lawyer—an honor held by only a small percentage of Texas attorneys. He earned his law degree from Baylor University School of Law and has spent more than 20 years helping injury victims across Dallas, Fort Worth and Austin. Mark handles cases involving car accidents, truck accidents, product liability, wrongful death, catastrophic injuries, and more. Click here to view some of the successful case results Mark has achieved for his clients.
Location: Dallas, Fort Worth, and Austin, Texas
Justia / LinkedIn / Yelp / Facebook / Instagram / X / TikTok / Youtube